
Adani, Tata Power and NTPC Split Over Whether India's Private Nuclear Push Should Go Local or Foreign
With draft rules for private nuclear power due for industry feedback by September 4, India's conglomerates are divided between backing indigenous PHWR designs and importing proven foreign reactor technology.
Manik Gupta
Founder and editor of DeepTech India. Manik writes about India's frontier technology ecosystem — AI, semiconductors, space, quantum, robotics and biotech — translating research and policy into clear, reliable reporting.
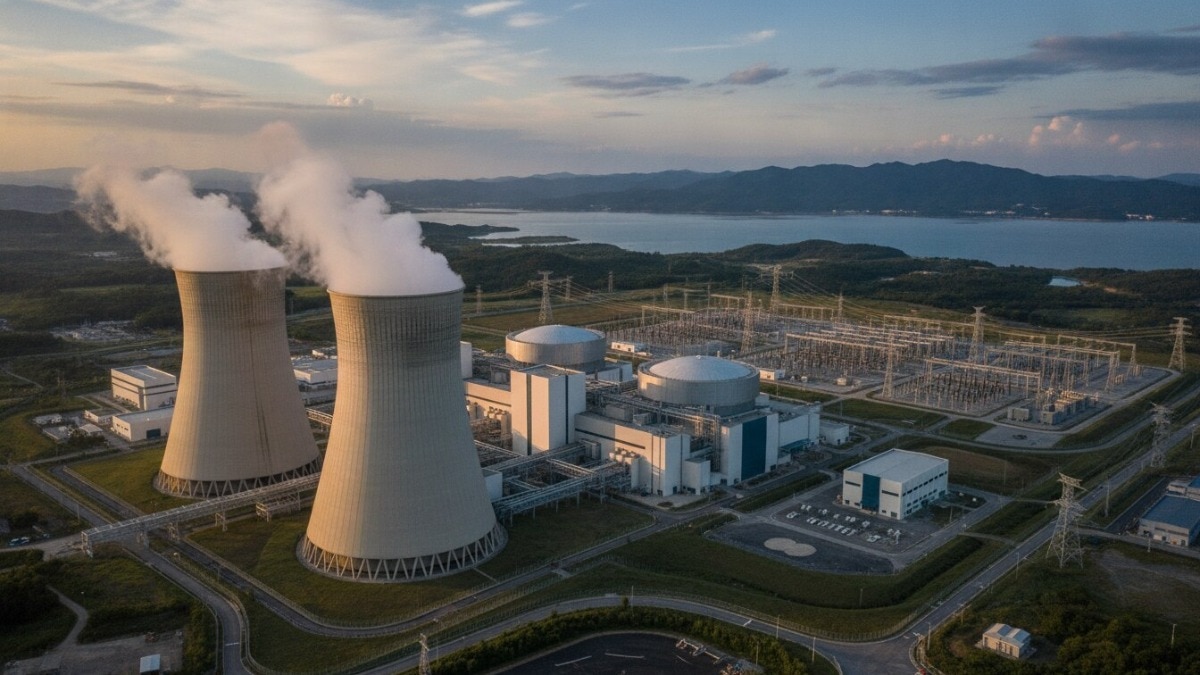
India's biggest industrial groups are quietly disagreeing with the government's own preferred starting point for private nuclear power — and the deadline to argue about it is days away.
The Split
As India's civil nuclear sector opens to private capital for the first time, two camps have emerged among the conglomerates lining up to build reactors. On one side, representatives of NTPC, Adani Atomic Energy and Jindal Steel argued at a BloombergNEF Summit panel in New Delhi that the country's existing 700 MWe Pressurised Heavy Water Reactor (PHWR) design is the sensible starting point — it has established design standards, a mature domestic supply chain, and an existing vendor ecosystem, since it's the only nuclear technology currently proven and licensable in India. Their proposed sequence: deploy 700 MWe PHWRs in fleet mode first, add pressurised water reactors (PWRs) next, and bring in small modular reactors (SMRs) only once those are further along.
On the other side, reporting this week indicates that Adani Power and Tata Power — alongside Reliance Industries, JSW and Jindal Nuclear Power Private Limited — have opened separate discussions with foreign reactor vendors including Russia's Rosatom, France's EDF, and US-based GE Hitachi and Westinghouse, exploring both large foreign reactors and foreign SMR designs still under active development globally.
Why the Local Option Has a Gap
The domestic PHWR route sounds like the obvious default, but it comes with an inconvenient fact: India's 220 MWe PHWR design hasn't seen a new deployment since 2011, and the manufacturers that once built compatible nuclear-grade turbines for that design have since stopped production. To close that gap, the Nuclear Power Corporation of India Ltd (NPCIL) is now working to adapt the 220 MWe PHWR blueprint into a new "Bharat Small Reactor" (BSR) design — adding steel liners and upgraded control and instrumentation systems to bring the decade-old design up to current safety expectations, rather than simply restarting old production lines.
Foreign large reactors, by contrast, come with a steep price tag: industry estimates put average costs at roughly ₹35 crore per megawatt, meaning a single 2,000 MW installation could run close to ₹70,000 crore. That cost, plus the multi-year lead time typical of large reactor projects globally, is part of why some players are hedging toward foreign SMR designs instead — smaller, factory-buildable units that in theory offer faster deployment, even though the technology itself remains commercially unproven anywhere in the world at scale.
The Rulebook Everyone Is Waiting On
The reason this debate is playing out publicly right now is regulatory: India's draft rules for private nuclear participation, released in August 2026 under the SHANTI Act framework, set out the licensing, safety-oversight, captive-generation and liability framework for the newly opened sector — including, critically, the conditions under which imported reactor designs can be deployed. Under the draft framework, companies seeking to use foreign reactors need operating and licensing certification from the reactor's country of origin, plus a separate design approval from India's own atomic energy regulator, before construction can even begin.
Industry stakeholders have been given until September 4, 2026 to submit feedback on the draft rules. Companies contacted for comment — including Tata Power, Adani Power, Reliance Industries, and the foreign vendors Rosatom, EDF and GE Hitachi — have largely declined to respond publicly ahead of that deadline, suggesting most are waiting to see the final rulebook before committing capital either way.
Why This Matters Beyond One Policy Debate
The stakes go well past a single design choice. India has set a target of five indigenously developed SMRs commissioned by 2033 and a broader ambition of 100 GW of nuclear capacity by 2047, alongside three parallel SMR designs already in development at BARC — the 200 MWe Bharat Small Modular Reactor, a 55 MWe SMR at Tarapur, and a high-temperature gas-cooled reactor for industrial and hydrogen applications. If the largest private players end up defaulting to imported large reactors or foreign SMR licenses rather than India's homegrown designs, it could undercut the domestic manufacturing and supply-chain ambitions those indigenous programmes were partly built to serve — even as it might get new capacity online faster in the near term.
Conversely, if the NTPC-Adani Atomic Energy-Jindal Steel camp is right that PHWR-first is the pragmatic path, the pressure shifts back onto NPCIL to prove the Bharat Small Reactor adaptation can actually be manufactured at scale, rather than remaining a paper design while foreign vendors sign the first real contracts.
What to Watch
The September 4 feedback deadline is the immediate marker, but the more consequential test comes after: how India's atomic energy regulator balances local content requirements against the practical reality that some private players clearly want proven foreign technology now rather than a domestic design still being adapted. The final rules will effectively decide whether India's newly opened private nuclear sector becomes a showcase for indigenous reactor technology or a fast-tracked entry point for global reactor vendors — and that choice, wired into rules due within days, will shape reactor orders for a decade.
Sources
- Why Adani and Tata Power are turning to foreign nuclear reactors over local models
- Why India's private nuclear entrants prefer PHWRs over small modular reactors—at least for now
- India's nuclear ambitions may be blunted by limits on foreign reactor tech
- India opens nuclear power sector to proven foreign reactor technology
Tags
More from Energy Tech
Magna Doubles Down on Yuma Energy With $35 Million to Scale India's Battery-Swapping Network
Automotive supplier Magna International has put a further $35 million into Yuma Energy, the battery-swapping venture it co-founded with Yulu, to expand the network past 60 million swaps.
India Weighs a ₹13,000 Crore Push to Build the Battery Materials It Still Imports From China
A proposed incentive scheme would target anode, cathode, electrolyte, separator and copper-foil manufacturing — the upstream layer India's battery gigafactories still depend on Chinese suppliers for.